Home / Flood Insurance

Frisco Flood Insurance: The policy your home insurance leaves out.

A standard homeowners policy doesn't cover flood. We help homeowners in Frisco and across North Texas compare NFIP and private flood options where available, before the next flash flood sends a creek over its banks.

$0Flood Coverage In A Home Policy
$250kNFIP Building Limit
30 DaysNFIP Waiting Period
IndependentLocal To Frisco
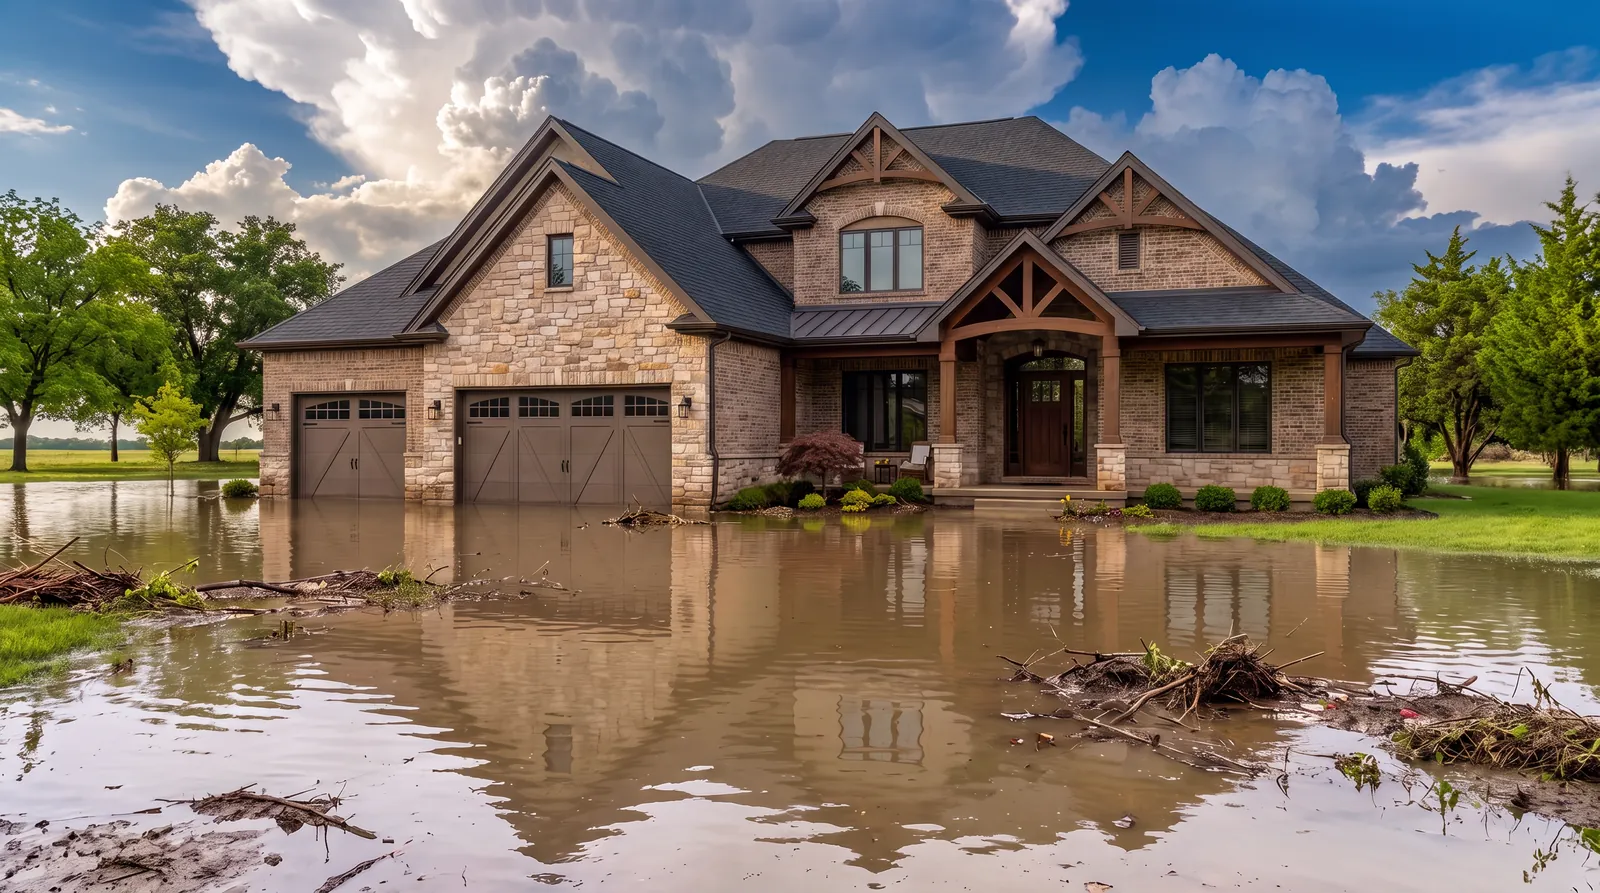
Floodwater surrounding a stone house after heavy rain
The Quick Answer

Standard homeowners insurance excludes flood. Rising water, flash flooding and creek overflow need a separate flood policy, most often written through the National Flood Insurance Program (NFIP). NFIP limits are $250,000 for the building and $100,000 for contents, and a new policy generally has a 30-day waiting period unless it's bought in connection with a loan closing. Lenders require flood coverage in high-risk zones (Special Flood Hazard Areas) for federally backed mortgages, but flash flooding from a slow-moving North Texas storm can push creeks and storm drains across Collin and Denton Counties over their limits and reach homes outside those zones too. Water from a sewer backup is not a flood claim; it's covered only if your home policy has a water backup endorsement. A car caught in floodwater is a comprehensive claim on your auto policy. 33° North Insurance Group is an independent agency in Frisco, Texas, led by Robert Hutchings. We can compare NFIP and private flood options where available. Call (972) 987-0650.

Home policy pays
$0 for flood
NFIP limits
$250k building / $100k contents
Waiting period
30 days (none at loan closing)
Free quotes
(972) 987-0650
Frisco Flood Insurance, The Short Version

The policy most North Texas homes don't have. Yet.

Here's the part that surprises almost everyone, so we'll put it first: your homeowners policy doesn't cover flood damage. Rising water, flash flooding and overflow from creeks, rivers and overwhelmed storm drains are excluded from standard home policies. It doesn't matter how long you've had the policy. Flood coverage is its own policy, usually written through the federal National Flood Insurance Program (NFIP).

The second thing to know is how flooding shows up here. It's usually not a slow rise. It's flash flooding, when a slow-moving spring or fall thunderstorm drops heavy rain on clay soil and acres of pavement faster than creeks and storm drains can carry it away. Streets, underpasses and low-water crossings across Collin and Denton Counties can go from dry to dangerous fast. Lenders only require flood insurance in high-risk zones, but the zone that triggers the mandate and the water that reaches your house don't always line up.

The third thing is the drains. Most Frisco homes sit on a slab, so water usually arrives one of two ways. If it rises from outside, that's flood. If it comes up through a drain or toilet because the sewer line backed up, that's a water backup loss. It's handled by your homeowners policy, and only if you added a water backup endorsement. We'll help you check both.

That's the offer. As an independent agency, we work for you, not an insurance company. We'll look up your flood zone, compare NFIP and private flood options where available, size the building and contents limits to your actual house, and show you how the flood policy fits next to your home and auto coverage. Call (972) 987-0650.
What a flood policy covers. And what it doesn't.

A flood policy is simpler than a homeowners policy. There are two main coverages plus a code-upgrade benefit. Its limits, definitions and gaps are where claims go sideways, so here's the map.

Building
Up to $250k NFIP

Building Property

The structure itself: foundation, walls, electrical and plumbing, HVAC and water heater, built-in appliances and attached fixtures. The NFIP caps this at $250,000. If your home would cost more to rebuild, we can compare private flood options where available.

Contents
Up to $100k NFIP

Personal Property

Furniture, clothing, electronics and the rest of what you own, on its own limit and deductible. The catch: the NFIP pays contents at actual cash value, meaning depreciated worth, not replacement price. Keep that in mind when you choose the limit.

ICC
Up to $30k

Increased Cost of Compliance

If a flood leaves your home substantially damaged, local rules can require you to rebuild to current floodplain standards: elevated, floodproofed or relocated. ICC adds up to $30,000 toward those costs. Most people don't know they have it.

Definition
Read this one

What Counts as a Flood

The NFIP definition: surface water covering two or more acres of normally dry land, or two or more properties, at least one of them yours. Rising water from a creek, the river or overwhelmed street drainage qualifies. A pipe bursting inside the house does not. That claim belongs to your home policy.

Deductibles
Two of them

Building & Contents Deductibles

A flood policy has separate deductibles for building and contents, chosen when you buy. Raising them lowers the premium. Just pick numbers your savings can actually cover the week after a storm, when other bills are also due.

Above the cap
Over $250k

Private Flood Options

Some homes would cost more than $250,000 to rebuild, and the NFIP building limit stops there. Private flood policies are another option in some cases. As an independent agency, we can compare NFIP and private flood options where available.

Not flood
Drains

Sewer Backup

Water that backs up through a drain or toilet because the sewer line is overwhelmed is a water backup loss, not a flood. Standard home policies usually exclude it unless you add a water backup endorsement to your homeowners policy.

Not covered
Living costs

Temporary Housing (NFIP)

The NFIP doesn't pay for rent or hotels while your home is unlivable. Plan for it with emergency savings. Homeowners loss-of-use coverage generally doesn't respond to a flood either.

Not covered
Vehicles

Cars & Trucks

A flooded vehicle isn't a flood-policy claim. It's covered by the comprehensive coverage on your auto policy, if you carry it. Underpasses and low-water crossings across DFW can flood fast in a heavy storm, so think twice before dropping comprehensive.

Not covered
Outside

Land, Pools & Landscaping

Flood insurance rebuilds the house, not the yard. Land, fences, pools, decks and landscaping are excluded. Coverage is also limited for finished space and belongings below the lowest elevated floor.

Do you actually know your flood zone?

Most homeowners are guessing. We'll look up your zone, compare your options and walk you through what a flood policy would cost for your address.

Coverage Basics

The four decisions that shape your flood policy.

Flood insurance looks simple until you read the policy. These are the choices that decide what a claim actually pays.

1. NFIP or private flood, compared for you

The National Flood Insurance Program is the federal flood program: standardized coverage with set limits, sold through insurance agents. Private flood policies are also available in some cases, with their own terms. Because we're an independent agency, we can compare NFIP and private flood options where available and explain the differences in plain English.

Flood rarely happens in isolation. The same storm that fills a creek can drop hail on the roof, flood a car and back up a drain. Keeping your home, auto and flood coverage with one local agency means one team that knows the whole plan, and one number to call: (972) 987-0650.

2. The building limit, and the cap above it

Your building limit should track what it costs to rebuild the house, the same logic as your homeowners dwelling limit. The NFIP stops at $250,000. If your home would cost more to rebuild, we'll look at what's available above that limit.

3. Contents, the coverage people skip

Building and contents are separate choices, and skipping contents to save money is a common regret. Watch the settlement basis: the NFIP pays contents at depreciated actual cash value, not replacement cost. After two feet of water in a house full of furniture and appliances, that difference adds up.

Renters aren't exempt. A landlord's flood policy covers the building, never your belongings. A contents-only flood policy exists for exactly this.

4. Your rate, your elevation and the glide path

Under FEMA's Risk Rating 2.0, your NFIP price is based on things like elevation, distance to flooding sources, foundation type and rebuild cost. An elevation certificate is optional, but FEMA will use one if it lowers your rate. On a well-graded or elevated lot it can be worth a look.

Annual increases on an existing NFIP policy are capped, which creates a glide path: the longer a policy has been in force, the further below full-risk price it may sit. That policy can be assumed by a buyer at closing, so "can I take over the seller's flood policy?" is a smart question when you buy a home.

Already have a flood policy? Send it over.

Building limit, contents, deductibles and whether the limits still fit the house you live in today. We'll also check whether your home policy has water backup coverage. No pressure either way.

Flood Zones, Explained Plainly

Zones, creeks and what the flood map doesn't tell you.

You've seen the maps and heard the letters. Here's what they mean for your address.

How the zones work

FEMA maps sort property into zones. A and AE zones are high-risk Special Flood Hazard Areas with at least a 1 percent chance of flooding each year, often called the "100-year" floodplain. If your home is in a high-risk zone and has a federally backed mortgage, your lender will require flood insurance. Zone X areas are moderate or lower risk, and coverage there is optional.

In North Texas the higher-risk areas generally follow the creeks and drainage channels that run through neighborhoods in Frisco and across Collin and Denton Counties. Frisco takes part in the NFIP, so flood coverage is available to homeowners and renters in the city. Zones can change from one street to the next, so we look up the map for your specific address instead of guessing by town or subdivision.

The map is not the risk

The map that triggers the lender requirement and the water that actually reaches homes are two different things. FEMA has long pointed out that many flood claims come from outside high-risk zones. Here that can look like a street that turns into a channel during a spring downpour, a storm drain that backs up during a cloudburst, or a creek that stays in its banks for years until the night it doesn't.

Federal disaster assistance isn't a plan, either. It requires a presidential disaster declaration, much of it comes as loans that must be repaid, and grants are typically a small fraction of real repair costs. Lower-risk addresses often have some of the lowest flood pricing, so it's worth getting a quote before deciding to skip it.

Risk Rating 2.0, map changes and the 30-day clock

The NFIP prices each property individually under Risk Rating 2.0. Zones still control the lender requirement, but not your NFIP price. Increases on an existing policy are capped year to year, so a policy bought early rides a glide path below full-risk pricing.

Flood maps also change. FEMA and local communities revise them as new studies are done, and a revision can move a property into a high-risk zone and trigger the lender requirement. And because a new NFIP policy usually waits 30 days to take effect, the time to buy is before spring storm season, not the afternoon a flash flood watch goes out.

Near a creek, or a street that floods?

Storms don't wait 30 days, and your flood coverage shouldn't either. Let us look up your zone and compare your options. No charge, no pressure.

Seven honest ways to manage your flood premium. Without hollowing out the policy.

With flood insurance, the biggest levers are timing and getting the rating details right, because each property is priced on its own. These may help lower what you pay.

1

Buy before storm season, and before any map change

A new NFIP policy generally waits 30 days to take effect, and coverage already in force when a flood map changes is generally better positioned than coverage bought after. Buying early also starts the glide path sooner.

2

Make sure your home is rated correctly

Details like foundation type, number of floors and where the HVAC and water heater sit all feed the price. We confirm the building details on your policy so you're not paying for a house you don't have.

3

Compare NFIP and private flood

Depending on the property, a private flood policy may be priced or structured differently than the NFIP. We can compare NFIP and private flood options where available and walk you through the trade-offs.

4

Ask about assuming the seller's policy

Buying a home that already has NFIP coverage? The policy can be assumed at closing, which may cost less than starting fresh at today's full-risk price. Ask before you close.

5

Get an elevation certificate if the lot favors you

It's optional under Risk Rating 2.0, and FEMA will use it if it lowers your rate. On an elevated foundation or a favorably graded lot, it can be worth the survey.

6

Choose deductibles your savings can cover

Building and contents deductibles are separate choices, and raising them trims the premium. Pick numbers you could actually pay the week after a storm, when a home policy deductible may be due at the same time.

7

Don't let it lapse

Continuous coverage protects your glide path. A lapse can reset you to full-risk pricing, and starting over usually means another 30-day wait. Set the flood policy on autopay.

Every flood situation is a little different. We'll help with all of them.

A creek out back, a closing date, a rental, a drain that backs up. Each one changes how your coverage should be built.

Under contract, or storm season coming?

Tell us the address. We'll look up the zone, compare NFIP and private flood options where available, and tell you what may lower the price. Straight answer, no obligation.

Flood insurance in Frisco. And across North Texas.

Flood pricing is property by property, and two streets in the same neighborhood can sit in different zones. We're local to Frisco, and we write flood coverage across Collin and Denton Counties and all of Texas.

Flood insurance questions. Straight answers.

Doesn't my homeowners insurance cover flooding?

No. Standard homeowners policies exclude flood: rising surface water, flash flooding and overflow from creeks, rivers and drainage. The exclusion applies no matter how long you've had the policy.

The dividing line is where the water came from. A pipe bursting inside the house is sudden internal water damage and belongs to your home policy. Water rising from outside belongs to a flood policy.

Is water from a backed-up drain a flood claim?

It depends on how it got there. If surface water from outside rose into the house, that's flood. If water came up through a drain or toilet because the sewer line backed up, that's a water backup loss, not a flood.

Standard homeowners policies usually exclude water backup unless you add a water backup endorsement. Most Frisco homes sit on a slab, so this is about drains, not basements, and we recommend checking for it either way.

Am I required to buy flood insurance?

Only if your home is in a FEMA high-risk zone (a Special Flood Hazard Area) and has a federally backed mortgage. Then your lender will require it.

Outside those zones it's optional. That's the trap: heavy rain doesn't stay inside the lines, and many flood claims come from outside high-risk zones. We'll quote it either way and let you decide with the number in front of you.

How much does flood insurance cost in Texas?

It depends on the property. Under Risk Rating 2.0, FEMA prices each address on factors like elevation, distance to water, foundation type and rebuild cost. A home backing onto a creek and one on higher ground nearby can see very different prices.

Homes outside high-risk zones are often among the lower-priced to insure, which is why they're worth quoting. We can compare NFIP and private flood options where available and give you a real number for your address.

What does an NFIP flood policy cover?

Up to $250,000 for the building (structure, systems, built-in appliances) and up to $100,000 for contents, each with its own deductible. It also includes up to $30,000 of Increased Cost of Compliance toward rebuilding to current floodplain standards after substantial damage.

Know the two catches: contents pay at depreciated actual cash value, and the NFIP doesn't pay for temporary housing while your home is unlivable. Plan your limits and your emergency savings around both.

Can I get more than $250,000 of flood coverage?

The NFIP building limit is $250,000 and the contents limit is $100,000. Plenty of homes in Frisco and across DFW would cost more than $250,000 to rebuild, and then the NFIP alone falls short.

Private flood policies may offer other limits in some cases. As an independent agency, we can compare NFIP and private flood options where available and tell you plainly what fits your home.

Is there a waiting period for flood insurance?

NFIP policies generally take effect 30 days after purchase. The main exception: coverage bought in connection with making, increasing, extending or renewing a home loan takes effect at closing, with no wait.

That 30-day clock is why the time to buy is before spring storm season, not when a flash flood watch goes out. Once the water is rising, it's too late for that storm.

I'm not in a flood zone. Do I still need flood insurance?

Every address has a flood zone. The question is which one, and a lower-risk zone means lower risk, not no risk. Heavy rain can send creeks and storm drains over their limits and reach homes outside the mapped floodplain.

The useful part: lower-risk zones generally get lower pricing. The addresses where people skip flood coverage are often where it costs the least to carry. Get the quote before deciding.

What is Risk Rating 2.0?

It's how FEMA prices NFIP policies. Instead of pricing by flood zone alone, it rates each property individually on factors like elevation, distance to flooding sources, foundation type and rebuild cost. Zones still control the lender requirement, but not your NFIP price.

Increases on an existing policy are capped year to year, creating a glide path below full-risk pricing for long-held policies. That's one more reason to get covered early and stay covered.

Will FEMA disaster assistance cover me if I skip flood insurance?

Not in a meaningful way. Federal assistance requires a presidential disaster declaration, much of it comes as SBA loans that must be repaid, and typical individual grants are a small fraction of real repair costs.

Assistance is a safety net, not a substitute for coverage, and many flood events never trigger a declaration at all. A flash flood that swamps a few streets may never make the news, but it still ruins the floors.

Does flood insurance cover my car or temporary housing?

No on both, under the NFIP. A flooded vehicle is a comprehensive claim on your auto policy. Think twice before dropping comprehensive, and never drive into moving water: turn around, don't drown.

The NFIP doesn't pay for rent or hotels while your home is unlivable. Build that into your emergency plan, and let us review your home and auto coverage alongside the flood policy so there are no surprises.

Can a flood policy transfer when a home is sold?

Yes. An NFIP policy can be assumed by the buyer at closing, and the seller's capped-increase glide path transfers with it. On a home that has carried flood coverage for years, that may cost less than starting a new policy at today's full-risk price.

It has to be arranged before closing. If you're buying near a creek, put "can I assume the flood policy?" on your checklist.

Can my flood zone change?

Yes. FEMA flood maps are revised as new studies are completed and as development changes how water moves through a watershed, and North Texas keeps building. A revision can move a property into a high-risk zone, which triggers the lender requirement for federally backed mortgages, or out of one.

Coverage already in force when a map changes is generally better positioned than coverage bought after. We check your zone when we quote and can look again at renewal.

Still have questions? Call (972) 987-0650. We'll give you a straight answer.

Find out what your flood risk really costs to cover.
Free, and in plain English.

Tell us the address. We'll look up the zone, compare NFIP and private flood options where available, and walk you through the numbers.